The global bond market is sending a signal that investors have seen before: when confidence in government debt, currencies and the purchasing power of money comes under pressure, gold has historically played an important role as a hedge.
The latest move in global bond yields is particularly striking.
Japan’s 10-year government bond yield recently reached 3% for the first time since 1996, while U.S. Treasury yields have climbed to levels not seen since 2007. Bond yields have also surged across Europe, with Germany and the UK reaching multi-year or multi-decade highs.
In other words, this isn’t simply a story about one country’s bond market.
The pressure is global.
When bonds stop behaving like the safe haven
For decades, government bonds have been regarded as one of the traditional defensive assets in a portfolio.
But bonds and yields move in opposite directions.
When investors sell bonds, bond prices fall and yields rise. If that selling occurs across several major sovereign markets simultaneously, it can indicate that investors are demanding greater compensation for holding long-term government debt.
Reuters reported that government borrowing costs from the United States to Germany and Japan are at or near multi-decade peaks, amid concerns about inflation, interest rates and government debt levels.
That creates a difficult environment.
Governments need to refinance enormous amounts of debt, while higher yields increase the cost of doing so. At the same time, inflation can reduce the real purchasing power of the interest and principal that bondholders ultimately receive.
And this is where gold has historically occupied a different position.
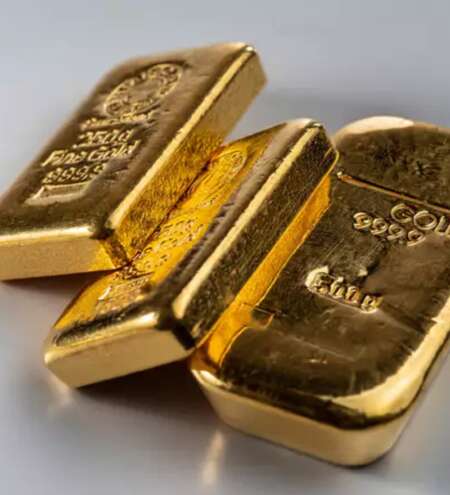
Gold is not somebody else’s liability
A government bond is a promise to pay.
Gold is not.
There is no government, corporation or bank standing behind a physical ounce of gold promising to repay the holder.
That characteristic has helped give gold a unique role throughout periods of monetary instability, currency weakness, inflation and financial stress.
J.P. Morgan Global Research describes gold as a debasement hedge, providing protection against loss of currency purchasing power through inflation or currency debasement.
The World Gold Council also identifies currency depreciation, portfolio hedging and geopolitical risk as important themes behind gold demand.
History keeps bringing investors back to the same question
The attraction of gold becomes particularly apparent when investors begin questioning the value of financial assets denominated in a particular currency.
During periods of monetary stress, gold doesn’t need to become a productive business, pay a dividend or generate an interest payment.
Its role is different.
It can act as a store of purchasing power outside the financial system.
That is why central banks themselves continue to hold gold.
The World Gold Council reported that central banks purchased 244 tonnes of gold on a net basis during the first quarter of 2026, despite gold prices being at record levels.
This is significant because central banks don’t buy gold because it pays a coupon.
They hold it because it provides diversification and represents a reserve asset that isn’t another country’s liability.
The bond market is flashing a warning about debt
The current environment isn’t necessarily predicting a financial crisis.
But it is highlighting a problem that is difficult to ignore: the cost of borrowing is rising at the same time that governments are carrying historically large amounts of debt.
When Japan, the United States, Britain, Germany and France are all experiencing substantial increases in long-term borrowing costs, the issue becomes much broader than a single country’s fiscal position.
The question becomes:
Who ultimately absorbs the cost of all this debt?
Higher taxes?
Lower government spending?
Higher economic growth?
Inflation?
Or some combination of all four?
There is no simple answer.
But history suggests that when governments and currencies are under pressure, investors often increase their focus on assets that are not directly dependent on government promises.
Gold doesn’t eliminate risk
Gold isn’t a magic shield.
Its price can fall, sometimes sharply. It produces no interest or dividend, and it can underperform interest-bearing assets during periods when real yields are rising.
Even J.P. Morgan notes that gold can perform poorly when Treasury and other asset yields are rising because gold itself has no real yield.
But that is precisely why the historical role of gold is better understood as a hedge and store of value, rather than simply another asset competing with shares or bonds.
The bigger picture
The extraordinary part of the current bond-market move isn’t that one yield has reached a particular number.
It is the breadth of the move.
Japan.
United States.
United Kingdom.
Germany.
France.
When several of the world’s major bond markets simultaneously experience significant upward pressure on long-term yields, investors are being reminded that government debt isn’t automatically risk-free simply because it is issued by a government.
And that is one reason gold continues to attract attention.
For thousands of years, gold has had no government behind it, no central bank required to maintain its value and no promise of repayment.
It simply remains gold.
In an environment where the world’s largest economies are carrying enormous debt loads and long-term borrowing costs are rising, that independence is precisely what gives gold its historical appeal as a hedge.
The FirstGold view
The question isn’t whether bonds, shares or gold will perform best next week or next month.
The more fundamental question is:
How much of your wealth do you want dependent on somebody else’s promise to pay?
Gold offers something fundamentally different: physical ownership of an asset that isn’t a debt owed by someone else.
And when the global bond market is on fire, that distinction becomes difficult to ignore.
Disclaimer: This article is for general information only and is not financial advice.
Sources: Reuters — Global bond sell-off and rising government borrowing costs · World Gold Council — Gold Demand Trends Q1 2026 · World Gold Council — Gold as a strategic asset · J.P. Morgan Global Research — Gold and currency debasement.